by Brian Thompson | Aug 26, 2026 | Employee Benefits, Identity Theft
A small town government in Maine lost $189,199 in May 2026. Staff wired a routine payment to a “vendor” that had supposedly updated its payment details. The vendor never sent that email. A criminal did. Nine hundred miles away, a homeowner found the same trick working a different angle. Someone had quietly filed a change of address with USPS, rerouting bank statements and credit card offers to an apartment three states away. Different targets, same move. This is why change of address monitoring has become one of the more overlooked pieces of identity protection.
Last Updated: August 2026
Both incidents above share a mechanic that fraud investigators see constantly. Control where something goes, and you control what happens to it next. Redirect a person’s mail and you get first access to new credit cards and bank statements. Redirect a business’s payment and you get the money directly, with no theft of the underlying account required. The tactic itself is old. What has changed by 2026 is the volume, the sophistication, and the way it now hits SMB owners and their employees from two directions at once.
What Change of Address Monitoring Actually Catches
Change of address monitoring watches for one thing. It flags whether someone has filed a request to redirect your mail, and whether that request actually came from you. USPS processes more than 33 million change of address transactions every year. The overwhelming majority are people moving, exactly as intended. The problem is the minority that are not.
Fraudulent change of address requests do not require access to your home or your mailbox. In many cases, a criminal only needs your name and old address. That information often turns up through data broker sites, prior breaches, or a piece of mail pulled from an unlocked box. Once the redirect goes through, the thief gets a window, sometimes weeks, before missing bills tip you off. That window is when the real damage happens. A redirected bank statement reveals account numbers and spending patterns. A redirected credit card offer can be activated in your name without you ever seeing it arrive. Some thieves use intercepted mail to intercept one-time verification codes sent by banks or brokerages, which lets them pass identity checks that would otherwise stop them. None of these steps require breaking into an account. They only require controlling where your mail lands.
How Criminals Redirect Mail, Then Money
The scale here is bigger than most people assume. A USPS Office of Inspector General report released in May 2026 found that the Postal Inspection Service received more than 800,000 mail theft complaints between fiscal years 2023 and 2025. Complaints rose again in fiscal year 2025 across nearly every Postal Inspection Service division. This pattern has been building for years. An earlier Inspector General analysis found that online change of address fraud jumped 167 percent in a single year. Cases went from 8,857 in 2020 to 23,606 in 2021, a spike documented in a 2022 congressional letter pressing USPS for stronger identity checks.
USPS responded by rolling out two-factor identity verification for online change of address requests in 2023. That closed off one entry point. It did not close all of them. Criminals still use forged paper forms, in-person requests with stolen ID, and look-alike websites that mimic the real USPS portal. Each of these collects personal and payment information under false pretenses. None of this requires a sophisticated hacker. It requires patience, a name, an old address, and the knowledge that most people do not check their mail forwarding status the way they check a bank balance.
The Business Version: Vendor Payment Redirect Fraud
SMB owners who treat this as a consumer problem are missing the half that costs the most money. The FBI’s Internet Crime Complaint Center describes a textbook business email compromise scenario in plain terms. A vendor your company regularly deals with sends an invoice with an updated mailing address, except the vendor never sent it. A criminal compromised or spoofed the vendor’s email and asked for future payments to go somewhere new. That single sentence describes the exact fraud that cost Harpswell, Maine nearly $190,000 this year. It also describes thousands of similar cases nationwide.
The numbers back up how expensive this has become. According to the FBI’s 2025 Internet Crime Report, business email compromise generated $3.05 billion in reported losses in 2025. That came from 24,768 complaints, up from $2.77 billion the year before. The report also notes that most BEC losses move by wire transfer or ACH. Both clear fast and are hard to reverse once the money lands. For a small business, one successful vendor payment redirect can wipe out a quarter’s margin in a single transaction.
This is a distinct threat from the personal mail fraud described above, and the distinction matters. Personal change of address monitoring protects an individual’s identity, credit file, and mail. It does not protect a company’s accounts payable process from a spoofed vendor email. That takes internal controls instead: verified callback numbers, dual approval on payment changes, and staff training on the exact pattern the FBI describes. The two threats share a root cause, an unverified change of address, but they need two different fixes.
Warning Signs You Are a Target
- Missing mail: Bills, statements, or credit card offers that simply stop arriving, especially all at once.
- An unexpected change of address confirmation: USPS sends a confirmation to both the old and new address for every change filed. Treat one you did not request as an active incident.
- New credit inquiries or accounts you do not recognize: A common next step once a thief controls your incoming mail.
- A vendor email requesting updated payment or address details: Especially one with urgency, or one that asks you to skip your normal verification “just this once.”
- A slightly altered vendor email domain: A single swapped letter is often the only visible tell in an otherwise convincing message.
How to Strengthen Change of Address Monitoring for Your Household and Your Business
For individuals and families, the fix is layered but not complicated. Enroll in change of address monitoring as part of a broader identity protection plan. That way, any USPS forwarding request tied to your name triggers an alert before mail actually starts moving. Check your credit file periodically instead of assuming no news is good news. Go directly to usps.com for any postal transaction. Do not click a search ad or an email link, since look-alike sites are built to catch people mid-move, right when they are least likely to double check a URL.
For businesses, the fix lives in process, not software alone. Any request to change a vendor’s payment details or address should require a verification call. Use a phone number you already have on file, never one provided in the request itself. Put dual approval on payment detail changes so one compromised inbox cannot redirect funds alone. Train accounts payable staff specifically on the vendor email compromise pattern, since general phishing training often skips this scenario entirely.
One employer-side move connects both problems at once. Offering identity theft protection, including change of address monitoring, as a voluntary employee benefit protects your workforce’s personal identities. Meanwhile, your business can separately harden its own payment verification process. Employees who understand how address-based fraud works on a personal level are also more likely to catch the business version when it lands in their inbox.
Frequently Asked Questions About Change of Address Monitoring
What is change of address monitoring?
Change of address monitoring is a service that alerts you when someone files a change of address request with USPS using your name or personal information. It gives you a chance to catch and reverse a fraudulent mail redirect before it causes lasting damage.
How do I know if someone filed a fraudulent change of address on my mail?
Watch for a USPS change of address confirmation letter you did not request. Also watch for a sudden stop in expected bills or statements, or credit inquiries you do not recognize. USPS mails a confirmation to both the old and new address for every change filed, which is your earliest warning sign.
What should I do if my mail is being redirected without my knowledge?
Contact the U.S. Postal Inspection Service to report the fraud. Cancel the unauthorized forwarding request directly through USPS. Place a fraud alert with the three major credit bureaus, then review recent account statements for unauthorized activity.
Can businesses be targeted by change of address fraud too?
Yes. The business version usually shows up as a vendor payment redirect scam. A criminal spoofs or compromises a vendor’s email account, then asks for future payments to go to a new address or bank account. The FBI tracks this under business email compromise, which caused $3.05 billion in reported losses in 2025.
How can I verify a vendor’s request to update payment or address details?
Call the vendor using a phone number from a prior invoice or your existing records. Never call a number listed in the request itself. Confirm the change verbally before processing any payment to the new details.
Does the Postal Service verify who requests a change of address?
USPS added two-factor identity verification for online change of address requests in 2023 after fraud rates climbed sharply. The protection is not absolute, though. Forged paper forms, in-person requests using stolen identification, and look-alike scam websites can still get through.
Does identity theft protection cover vendor payment fraud for my business?
No. Personal identity theft protection, including change of address monitoring, protects an individual’s mail, credit file, and personal information. It does not replace internal accounts payable controls, which are the correct defense against vendor payment redirect fraud.
How long do I have to reverse a fraudulent change of address?
Act as soon as you notice a confirmation notice you did not request. USPS can cancel a pending or recent change of address request once you report it, but the window narrows the longer mail keeps flowing to the wrong location. Every week of delay gives a thief more time to open accounts or activate stolen cards using your redirected mail.
Change of address fraud is not a new threat. The 2026 version of it is faster, better documented in enterprise threat data, and increasingly aimed at the gap between what a person notices and what a business verifies. Whether it shows up as a stranger redirecting your mail or a criminal redirecting a vendor payment, the fix starts the same way. Treat any change of address as an event worth confirming, not assuming. Visit defend-id.com to see how change of address monitoring fits into a full identity protection plan for you and your family.
Related articles:
by Brian Thompson | Jun 26, 2024 | Employee Benefits, Identity Theft
Identity theft is a serious crime that can devastate your finances and your life. When someone steals your personal information, they can use it to open new accounts in your name, run up debts, and damage your credit score. Here we will discuss How to Protect Your Credit from Identity Theft.
A low credit score makes it difficult to get approved for loans, credit cards, and other forms of credit. It can also make borrowing money more expensive since you will likely have to pay higher interest rates. A low credit score also makes it difficult to rent an apartment, get a job, or even get insurance.
How Identity Theft Can Ruin Your Credit Score
Identity thieves can damage your credit in various ways. Here are a few examples:
- Opening New Accounts: Thieves can open new accounts in your name and not make payments, leading to collections and even bankruptcy.
- Maxing Out Credit Cards: They can max out your existing credit cards, significantly damaging your credit score.
- Changing Addresses: They can change the address on your accounts so you don’t receive important billing information, leading to missed payments and further damage to your credit score.
- Filing for Bankruptcy: Thieves can file for bankruptcy in your name, which will stay on your credit report for up to 10 years, making it very difficult to get approved for credit.
The Impact of a Low Credit Score Due to Identity Theft
A low credit score can significantly impact your life. Here are a few examples:
- Loan Approval: You may not be able to get approved for a loan to buy a car or a home.
- Higher Interest Rates: You may have to pay higher interest rates on credit cards and loans.
- Difficulty Renting or Getting a Job: You may have difficulty renting an apartment or getting a job.
- Insurance Issues: You may have difficulty getting insurance.
- Job Promotions and Scholarships: You may be denied a job promotion or a scholarship.
The Emotional Impact of Identity Theft
Identity theft not only ruins your credit but also has a significant emotional impact on victims. Victims may experience feelings of anger, anxiety, stress, and depression. They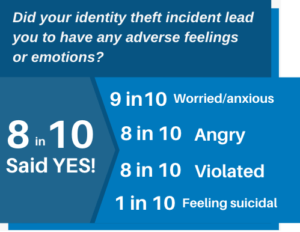 may also feel violated, betrayed, and helpless.
According to a study by the Identity Theft Resource Center, 70% of identity theft victims experience emotional distress. The study also found that victims are more likely to experience anxiety, depression, and post-traumatic stress disorder (PTSD) than people who have not been victims of identity theft.
If you are a victim of identity theft, it is important to seek help from a mental health professional. Talking to someone about what you are going through can help you cope with the emotional impact of the crime.
Steps to Recover from Identity Theft
If you find yourself a victim of identity theft, don’t panic. Here’s a systematic guide to help you regain control and mitigate any potential damage:
- Notify Your Insurance Provider: If you have identity theft insurance, inform them first for guidance and help.
- Alert Your Financial Institutions: Contact your bank and credit card issuers immediately to halt transactions and secure accounts.
- Contact Affected Companies: Reach out to companies where the theft occurred to inform their fraud department.
- Implement a Fraud Alert: Place a fraud alert on your credit with one of the three major credit bureaus.
- Review Your Credit Reports: Access your free credit reports from AnnualCreditReport.com and report any discrepancies.
- File a Report with the FTC: Visit identitytheft.gov to file a comprehensive identity theft report with the Federal Trade Commission (FTC).
- Report to Local Law Enforcement: Filing a police report provides an official record of the identity theft.
- Secure Your Online Presence: Change all online account passwords, consider using a password manager, and activate two-factor authentication.
- Replace Important Documents: Apply for replacements for stolen IDs like your driver’s license, passport, and Social Security card.
- Subscribe to Identity Theft Protection Services: Consider services like defend-id which monitor your financial and digital presence, providing alerts and insurance.
Steps to Take if You Suspect Identity Theft
If you suspect you’ve fallen victim to identity theft, take these essential steps promptly:
- Contact Your Financial Institutions: Reach out to your bank and credit card issuers immediately to freeze your accounts and halt unauthorized transactions.
- Report to Your Identity Theft Insurance Provider: Notify your provider right away for guidance and resources, including legal and financial assistance.
How Identity Theft Protection Services Help
Identity theft protection services, such as defend-id, play a crucial role in safeguarding your online and financial accounts from fraudulent activities. With defend-id’s advanced monitoring technology, subscribers receive alerts about potential fraud approximately four times faster than many competing services.
- Comprehensive Monitoring and Swift Alerts: defend-id provides detailed monitoring by keeping track of your personal and financial account activities. If something unusual is detected, defend-id promptly sends out an alert.
- Robust Insurance Coverage: defend-id offers significant financial protection with an insurance policy that can provide up to $1,000,000 in compensation for eligible losses caused by identity theft.
Protecting Yourself from Identity Theft and Fraud
Protecting yourself from identity theft and fraud is crucial. One effective way to safeguard your personal information is by using comprehensive services like defend-id, which offers robust monitoring and insurance coverage.
- Comprehensive Insurance Coverage: defend-id provides each plan member with a $1,000,000 insurance policy.
- Real-Time Monitoring and Alerts: defend-id monitors your financial and online accounts continuously, alerting you swiftly to any suspicious activity.
- Family Protection: defend-id’s Family Plan extends protection to up to five family members, including both adults and children.
- Trial Period: defend-id offers a 14-day free trial, allowing you to experience their service before committing.
Taking proactive steps by enrolling in a service like defend-id can provide peace of mind and significantly reduce the chances of suffering from identity theft and fraud.
Tactics Used by Identity Thieves
Identity thieves deploy various tactics to access personal data. They might steal your wallet, ID, or mail containing personal information, use a change-of-address scam, send phishing emails, texts, and calls, buy your data off the Dark Web, hack into your email, or intercept your data on an unsecured Wi-Fi network. Understanding these methods allows you to be more vigilant and take preventative measures to secure your personal and financial information.
Take Action Today
Identity theft is a serious crime, but you can protect yourself by taking necessary steps to safeguard your personal information and monitoring your credit reports regularly.
Resources:
- The Federal Trade Commission (FTC): 1-877-438-4338
- The Identity Theft Resource Center: 1-888-400-5530
- The National Association of Consumer Advocates: 1-800-644-7222
Don’t let identity theft ruin your credit and your life. Take action today to protect yourself!
Articles related to How to Protect Your Credit from Identity Theft:
by Brian Thompson | Aug 9, 2023 | Identity Theft
Wifi Safety: Don’t Fall for This Sneaky Trick! Do you use public WiFi? It’s a handy way to stay online while you’re out and about. But be careful! There’s a new trick called WiFi jacking that can steal your info.
Bad guys use a special tool to sneak into public WiFi networks. They can get into your phone and take your personal stuff. This is a big problem, but we can protect ourselves.
WiFi Jacking: A Sneaky Trick Crooks use a strong antenna to do WiFi jacking. They aim it at public WiFi spots and take info from people who are connected. They can grab things like passwords and credit card numbers.
This is really bad because they can use your info to do bad stuff like stealing money or pretending to be you. We need to be careful when we’re on public WiFi.
WiFi Jacking vs. Man-in-the-Middle WiFi jacking sounds like another trick called Man-in-the-Middle. But they’re a bit different.
WiFi jacking steals info from WiFi networks. Man-in-the-Middle attacks mess up conversations between two people online. Both are bad, but WiFi jacking is more about taking info from wireless networks.
Watch Out for Risks WiFi jacking is a problem because it tricks us on public WiFi. We think we’re safe, but the bad guys are listening. We have to be smart and keep our stuff safe.
Here’s what you can do:
- Use Safe WiFi: Pick trusted networks, not ones with strange names.
- Try VPNs: These make a secret path for your info so bad guys can’t take it.
- Use 2FA: Add an extra step when you log in, like a special code sent to your phone.
- Check Websites: Look for “https://” and a lock symbol when you visit a site. That is an indication that it’s safe.
- Update Stuff: Keep your phone and apps up to date. This helps stop bad guys.
Stay Safe and Smart WiFi jacking is a problem, but we can beat it. Connect smartly, use a VPN, try 2FA, and watch out for weird stuff online. Let’s make sure our info stays safe and keep having fun online!
Wifi Safety: Don’t Fall for This Sneaky Trick!
Related Articles:
by Brian Thompson | Mar 9, 2023 | Identity Theft
Open season for Tax Identity Thieves is in full swing. They are ready for you to procrastinate, to hold off on doing your taxes because they are ready to do it for you.
Tax identity theft occurs when the bad guy uses your Social Security Number (SSN) to file a fake tax return and collect your refund. You are unlikely to find out about it until you attempt to file your real tax return and it is rejected by the IRS as a duplicate. The fraudulent use of your SSN means you also may be at risk for other types of identity theft.
What to do.
-
Beat them to it and file your taxes as early as possible to ensure you do not become a victim. This is extremely important if you know your information has been part of any one of the data breaches over the years or if you have had your identity stolen in the past already.
-
Protect your Social Security Number whenever possible. You are often asked for your SSN on forms but it is not always necessary. Do not provide your SSN unless it is absolutely needed.
-
Beware of SCAMS. Lookout for Government imposters threatening fines, arrest or cancellation of your SSN if you do not pay them immediately. They will usually ask you to pay with a gift card or prepaid debit card. If you pay them, you will never see your money again. Some scammers will ask you to confirm your identity by providing your SSN, again, do not. Remember, the IRS will contact you first by mail. Additionally, the IRS will never email you, send you a text or contact you on a social network.
-
Secure your network. If you are filing electronically, use a secure, password-protected network or Virtual Private Network (VPN) connection to do so. You can also mail your returns directly from the Post Office, do not put them in your personal mailbox with the flag up!
-
Know your tax person! If you are using someone to prepare your taxes, you must go through your due diligence before you hand over your Personally Identifiable Information, (PII).
What if it happens to me?
- First, contact the IRS as soon as you can. Keep careful documentation of everything and stay in touch with the IRS until the issue is resolved.
- Second, file a complaint with the Federal Trade Commission.
- Third, file a complaint with the local police department.
- Fourth, put a fraud alert on your credit file with all three credit bureaus.
It is an open hunting season for identity thieves but we don’t have to be deer in headlights, take these steps and mitigate your risk.
Hunting season for Tax Identity Thieves is in full swing and its time to know your rights: PDF HERE
If you don’t want to fight this fight alone, get identity theft protection and mitigate your risks with monitoring, cover your losses with insurance and ensure peace of mind with a place to turn with full-service recovery experts. Read more about identity theft protection here: 14 features of Identity Theft Protection Monitoring and the Most Important Feature!